Refinancing a Manufactured Home: What You Need to Qualify
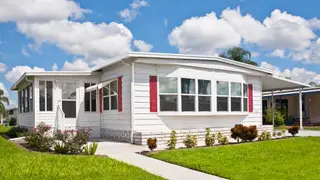
Refinancing a mobile or manufactured home is possible but requires the property to be classified as real estate on land you own, with a HUD-approved permanent foundation and built after June 15, 1976. Loan programs typically expect credit scores around 580 for FHA and 620 for conventional loans, with debt-to-income ratios near 43 percent. The home's age, size, and installation status heavily influence which refinance options are available.
Manufactured housing represents a significant portion of affordable homeownership in the United States, yet refinancing these properties involves stricter hurdles than traditional mortgages. The June 15, 1976 cutoff is critical because homes built before that date are generally classified as trailers or personal property, making them ineligible for most standard refinance programs. Additionally, the home must be permanently affixed to a HUD-approved foundation, have its wheels and axles removed, and be legally titled as real estate rather than personal property.
Lenders also evaluate the home's physical characteristics, including minimum square footage requirements and width standards, alongside borrower financials. FHA programs offer more lenient credit thresholds near 580, while conventional loans typically require around 620. The debt-to-income ratio benchmark of 43 percent serves as a common guideline, though individual lenders may apply flexibility depending on compensating factors such as larger down payments or substantial cash reserves.
This story may affect a substantial segment of homeowners who purchased manufactured housing as an affordable entry point into property ownership. Stricter refinancing requirements could limit access to lower interest rates and equity extraction for those with older homes or properties not classified as real estate. Borrowers with credit scores below 580 may find themselves locked into higher-rate loans, potentially widening the wealth gap between manufactured and traditional homeowners. However, clear eligibility guidelines could also help borrowers prepare strategically before applying.