P&G Offers Safer Dividend Income Than Kimberly-Clark Despite Lower Yield
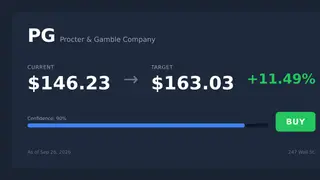
The comparison says Kimberly-Clark pays a higher yield, but its earnings and free cash flow provide less coverage for the dividend. Procter & Gamble has a 70-year dividend increase streak, stronger cash generation, and a smaller recent share decline. Kimberly-Clark has also faced a China diaper disruption and is pursuing a risky Kenvue acquisition.
Procter & Gamble and Kimberly-Clark both sell household staples, a sector retirees often favor for regular income. Kimberly-Clark offers the larger yield, yet its recent earnings and cash generation leave less room to cover the payout, while P&G’s core profit and free cash flow sit well above its dividend plans.
P&G has increased its payout for 70 consecutive years and paid dividends for 136. Kimberly-Clark’s increase streak is 54 years. Kimberly-Clark also absorbed a roughly $70 million China diaper hit and is pursuing a large Kenvue deal, while its stock has fallen more than P&G’s.
Retirees and income-focused investors may reassess holdings if they prioritize dividend durability over headline yield, potentially shifting flows toward P&G and away from Kimberly-Clark. Employees, suppliers, and communities linked to either firm could feel indirect effects through investment, restructuring, or acquisition integration. Consumers may see limited near-term change, though retailer bargaining power and private-label competition could gradually influence prices, product choices, and availability.