Safe Bulkers Poised for Upside as Costs Fall and Cash Margins Expand
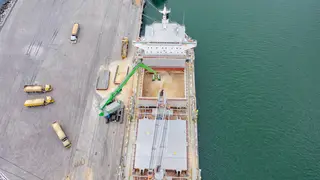
Safe Bulkers receives a Strong Buy rating with 26% upside and a 3.6% dividend yield, supported by structural time charter equivalent rate strength. Its 45-vessel dry bulk fleet is young, benefits from rising asset values, and has growing spot exposure in Capesize and Kamsarmax segments. Operating leverage is improving as OPEX falls and cash margins nearly double, while coal and steel demand provide tailwinds and the balance sheet supports higher payouts.
Safe Bulkers operates a 45-vessel dry bulk fleet described as young. The investment case cites structural time charter equivalent rate strength, a Strong Buy rating, 26% upside, and a 3.6% dividend yield. Its Capesize and Kamsarmax exposure includes growing spot market participation.
Falling operating expenses are said to nearly double cash margins, improving operating leverage. Coal and steel demand are cited as supportive forces. The balance sheet is presented as supportive of larger payouts, with a forward P/E as low as 4.7x under current conditions.
Investors in shipping equities could be affected if the thesis plays out, through dividends and share-price moves. Ports, shipbuilders, and commodity supply chains may also feel indirect effects if dry bulk demand and vessel values hold up. Broader consumers might see modest cost implications through coal and steel logistics, though outcomes remain uncertain and market-dependent.