Home Depot's Dividend Hinges on Frozen Housing Turnover
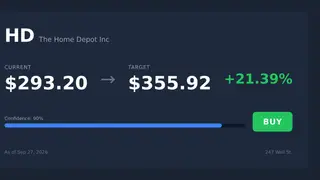
Home Depot's stock has fallen near a 52-week low, lifting its yield to 3.13%, while its $9.32 annual dividend is covered by $12.65 billion in free cash flow against $9.15 billion in payouts. Existing home sales fell to a 3.98 million annualized pace in August, and management said housing turnover has been low for four years with no clear inflection point. Pro contractors are offsetting weaker DIY demand, but Lowe's and Sherwin-Williams face similar pressure from delayed renovation projects.
Home Depot shares recently closed at $293.20, down 11.8% over a month and 25.98% over a year, close to a 52-week low of $284.85. That decline pushed the yield to 3.13%. Fiscal 2025 free cash flow was $12.65 billion, down 22.54%, while dividend payments totaled $9.152 billion.
Quarterly operating cash flow was $6.032 billion in Q1 and $5.39 billion in Q2, with capital spending of $844 million and $880 million. Dividends cost about $2.32 billion each quarter. Buybacks have effectively halted. Total debt is $62.567 billion against $2.085 billion cash, with net debt/EBITDA at 2.65.
If housing turnover stays subdued, homeowners may keep postponing moves and renovations, affecting contractors, suppliers, and retail workers tied to home improvement. Income-focused investors, including retirees, could feel reassured if Home Depot maintains its payout, though slower dividend growth may limit inflation-adjusted income. Lowe's and Sherwin-Williams may face similar demand pressure, potentially influencing hiring and store investment in communities where housing activity is weak.