Oracle's Large AI Backlog Could Support a Big Rebound, Analyst Says
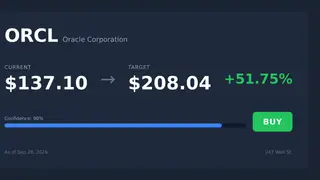
Oracle reported a strong quarter and holds $664 billion in remaining performance obligations, up $209 billion year over year, with management expecting about half to convert to revenue within 36 months. Despite that backlog and 121% cloud revenue growth, the stock trades near a 52-week low and at roughly 18 times forward earnings. 24/7 Wall St. has a $208.21 price target on Oracle, implying about 52% upside from its September 25 close of $137.08.
Oracle's latest quarter showed revenue of $19.34 billion, up 29.6%, beating estimates, while non-GAAP EPS was $1.92 versus $1.74 expected. Cloud infrastructure revenue climbed 121% to $7.39 billion. Its remaining performance obligations totaled $664 billion, $209 billion higher year over year, with management expecting roughly half to become revenue within 36 months.
Despite those results, shares closed at $137.08 on September 25, down 28.98% year to date and about 57% below the 52-week high. The stock trades near 18 times forward earnings, compared with 24 to 25 times for Microsoft and Amazon. A New Mexico data center force majeure notice and share pledges by Larry Ellison added pressure.
Oracle's backlog and AI expansion could affect retirement savers and workers whose funds or jobs are tied to tech. If contracts convert, data-center communities may see investment and energy demand, while investors may gain from a rebound. If conversion slows or debt rises, pension funds and individual shareholders could face losses. Customers may benefit from cloud capacity, but local resources and grid costs may draw scrutiny.