Connectivity Chipmaker Positioned to Capitalize on Evolving AI Infrastructure Demand
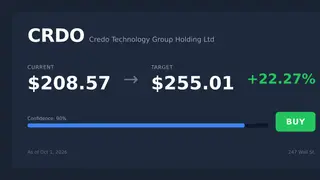
As artificial intelligence spending shifts from processors to interconnectivity solutions, Credo Technology has demonstrated 115% revenue growth while trading at significantly lower valuations than competitors. The stock trades at 27x forward earnings compared to peers Astera Labs and Marvell at 56x and 62x respectively, despite maintaining the fastest revenue growth in the sector. Analyst sentiment remains bullish with a price target of $242.79, though concentration with two major customers creates notable risk exposure.
Credo has emerged as a beneficiary of a fundamental shift in artificial intelligence infrastructure priorities. As enterprises deploy increasingly large AI systems, the bottleneck has moved beyond processor acquisition to the interconnection systems that link these components together. The company's optical and memory connectivity solutions address this emerging demand, with management projecting that optical revenue alone will exceed $600 million in fiscal 2027, distributed across three distinct product lines.
The valuation disparity between Credo and comparable firms suggests potential mispricing in the market. While peers Astera Labs and Marvell command multiples roughly double or triple Credo's forward earnings ratio, Credo maintains superior revenue growth rates. This gap could narrow if the company sustains its growth trajectory, though the recent 17% decline despite earnings beats illustrates how volatile semiconductor stocks can be during market corrections.
Credo's performance could influence how investors evaluate emerging technology subsectors and infrastructure bottlenecks. Success in connectivity solutions may redirect capital allocation within semiconductor and data center industries, potentially affecting competition among chipmakers and infrastructure providers. However, the company's heavy dependence on two major customers—representing 61% of revenue—concentrates benefits among a limited set of firms, potentially widening disparities in how AI infrastructure gains are distributed across the technology sector.