General Mills High Yield Masks Deteriorating Fundamentals as Dividend Faces Sustainability Questions
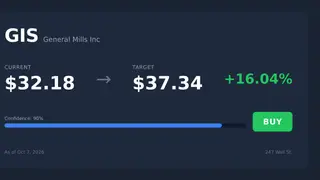
General Mills trades near decade lows with a 7.62% yield after declining 27% this year, but the company's frozen dividend, four times leverage relative to its three-time target, and shrinking profits suggest the high yield may be a warning sign rather than an opportunity. Revenue fell 5.45% to $18.42 billion in fiscal 2026 as consumers shifted to store brands, undermining management's pricing strategy and forcing a $1.75 billion write-down. Fiscal 2027 earnings guidance was cut to $3.00 to $3.20 per share from $3.55, while peers Kraft Heinz and Campbell's offer comparable yields at lower debt-adjusted valuations.
General Mills faces mounting pressure as its business fundamentals deteriorate despite offering an attractive dividend yield. The company's efforts to reset pricing strategy have backfired, with consumers increasingly trading down to cheaper store-brand alternatives rather than accepting higher prices. Revenue contraction, combined with a massive asset write-down primarily from its Blue Buffalo pet food acquisition, has created a difficult environment for management to navigate while maintaining shareholder returns.
The company's financial leverage presents another concern for investors. With debt levels substantially above management's stated targets, the organization has limited financial flexibility to weather further operational challenges or invest in brand revitalization. Cost-cutting programs and operational efficiency gains must now shoulder the burden of offsetting inflation while supporting a dividend that has remained frozen despite declining profitability and reduced earnings guidance.
General Mills' situation may concern both income-focused investors relying on dividend payments and workers employed across the company's operations. If financial pressure intensifies, the company could face difficult decisions regarding dividend sustainability or capital allocation priorities. Additionally, the shift toward store brands could reshape competitive dynamics in packaged foods, potentially affecting suppliers and employment throughout the industry value chain. Market observers may view this case as indicative of broader challenges facing legacy food manufacturers adapting to changing consumer preferences.