Physical Crypto Payment Card Manufacturer Faces Global Supply Constraints
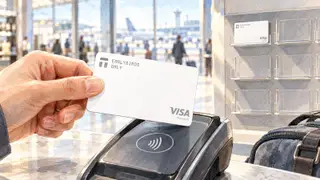
Tangem has launched a limited release of 5,000 physical Visa cards linked to cryptocurrency wallets but reports supply cannot meet demand in approximately 20 countries due to regulatory and banking infrastructure requirements. The company's card enables in-store purchases, online transactions, and ATM withdrawals funded from self-custodial wallets, with Latin America and the United States accounting for over 70% of transaction volume. Geographic availability depends on complex alignment of regulatory frameworks, banking rules, and card-issuance compliance rather than cryptocurrency regulations alone.
Tangem's initial rollout of 5,000 cards represents an early test of integrating cryptocurrency with traditional payment infrastructure. The service allows holders to spend directly from blockchain-based wallets at conventional retailers and withdraw cash, with funds remaining under user control rather than held by intermediaries. Transaction patterns reveal geographic concentration, with approximately 70 percent of activity originating from the Americas.
The unavailability in roughly 20 nations stems from overlapping compliance layers rather than cryptocurrency-specific bans. Regulated payment networks impose Know Your Customer protocols, sanctions screening, and card-issuance standards that operate independently from blockchain regulations. This distinction means countries may welcome crypto adoption while still blocking physical card distribution due to banking infrastructure misalignment or payment processor policies.
The supply constraints could affect adoption trajectories for hybrid financial products bridging crypto and traditional commerce. Users in restricted regions may experience delayed access to payment solutions, potentially fragmenting the user base geographically. Conversely, the rollout may demonstrate feasibility to other fintech firms, influencing how payment networks balance innovation with compliance. Banking infrastructure gaps highlighted here could prompt either regulatory harmonization efforts or alternative card-issuance models in underserved markets.