Apartment REITs May Benefit as Rental Supply Growth Slows
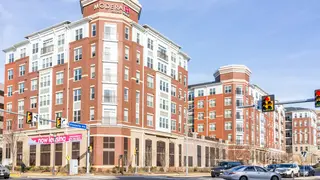
Apartment REITs are entering a potentially better period as a three-year construction surge fades and demand remains steady. The article examines four landlords—MAA, Essex Property Trust, Vivmark Residential, and Camden Property Trust—and compares their yields, leverage, and geographic exposure. It also notes that AvalonBay and Equity Residential completed their merger into Vivmark in August 2026, while Camden's Sunbelt pivot increased its leverage.
Apartment landlords endured three years of heavy construction that weighed on rents, but that wave is easing while tenant demand holds. MAA said second-quarter absorption ran at 1.8 times new deliveries. AvalonBay and Equity Residential merged on Aug. 17, 2026, forming Vivmark Residential, a 180,000-unit coastal owner. This review covers MAA, Essex, Vivmark, and Camden.
Essex focuses on West Coast markets with limited new supply; San Francisco is projected to add just 900 units in 2026. Camden sold its California portfolio for $1.6 billion, raising leverage from 4.2x to 5.3x net debt to EBITDAre, with $552 million maturing by year-end.
If construction slows while demand holds, renters in supply-constrained coastal markets could face less bargaining power and potentially firmer rent growth. Investors in apartment REITs may see steadier dividends, though Camden's higher leverage could amplify risks if conditions weaken. Merger consolidation may affect tenants through fewer owner choices, while Sunbelt renters could still benefit from elevated supply. Overall, outcomes may vary by region and household budget.