Financing an ADU or Home Addition With Home Equity
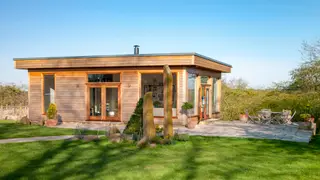
Homeowners can often use a home equity loan to pay for an accessory dwelling unit, garage conversion, or addition, provided they have enough equity and can handle the payments. A lump-sum home equity loan works well for fixed budgets, while a HELOC can be drawn in stages as construction proceeds. If available equity is insufficient, renovation or construction financing may be an option, but those products can involve more oversight and may replace the first mortgage.
A home equity loan can fund an ADU, garage conversion, or addition while leaving the original mortgage untouched. It usually arrives as one fixed-rate sum, creating a second lien; because the whole balance is advanced at closing, interest begins on that full amount right away.
Borrowing capacity depends on home value, current mortgage debt, the lender's combined loan-to-value cap, and the borrower's finances. A HELOC may suit staged construction payments, while renovation or construction loans can cover projects that exceed available equity, though they often involve added oversight and might replace the first mortgage.
This financing option may affect homeowners seeking to add housing, renters who could gain new units, and neighbors impacted by construction. If more ADUs and additions are built, local housing supply could increase modestly, while homeowners take on added debt and foreclosure risk. Lenders and contractors may see more demand, but outcomes depend on zoning, equity, and repayment ability.