Markets Mixed Amid Rate Hike Fears and Oil Inventory Build
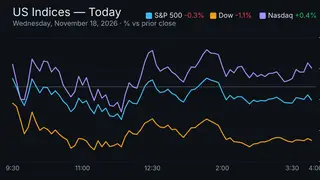
On Wednesday, November 18, 2026, markets closed mixed as hawkish FOMC minutes increased the likelihood of a December rate hike, pushing the 10-year Treasury yield to 5.09%. The Dow Jones fell 1.11%, while the Nasdaq rose 0.42% and the Russell 2000 gained 0.46%. Gold dropped 3.56% amid rising bond yields, and WTI Crude declined 3.05% due to a large U.S. crude inventory build, despite ongoing Middle East supply risks.
On Wednesday, November 18, 2026, global stock markets closed mixed amid heightened anxiety over potential interest rate hikes, as the Federal Open Market Committee’s (FOMC) recently released minutes revealed a hawkish stance, increasing the odds of a December rate hike to 94%. The 10-year Treasury yield rose to 5.09%, pressuring equities: the Dow Jones Industrial Average fell 1.11% to 50,198.17, while the S&P 500 dipped 0.23% to 7,323.63. In contrast, the Nasdaq Composite gained 0.42% to 24,429.89, and the Russell 2000 rose 0.46%, reflecting resilience in tech and small-cap stocks. Gold prices plummeted 3.56% to $3,726.50, and WTI crude oil dropped 3.05% to $82.07, despite ongoing Middle East supply risks, due to a surprise 5.28 million-barrel increase in U.S. crude inventories. The energy sector suffered, with Petroleum Refining down 6.25%, while gold and silver ores declined 4.41%. Meanwhile, retail and apparel stocks surged, led by Family Clothing Stores and Apparel, which rose 3.70% and 3.73%, respectively, after Target reported that tariff refunds contributed 19% to its Q3 earnings. Nvidia, despite beating revenue expectations, fell 2.89% amid concerns over tighter export controls and CEO Jensen Huang’s departure.
The broader market context reflects a pivot toward tighter monetary policy, driven by persistent inflation and the Fed’s commitment to price stability. The FOMC’s hawkish tone follows earlier rate hikes and signals a continued focus on controlling inflation, even as economic growth remains fragile. Investors are now pricing in a high probability of another rate increase in December, which could dampen corporate borrowing and consumer spending. Key players include the Federal Reserve, which seeks to balance inflation control with economic growth, and corporate executives like Jensen Huang, whose exit from Nvidia may influence investor sentiment in the tech sector. The upcoming Anthropic IPO, valued at $1.4 trillion, could further test market appetite for high-growth tech, while data releases on GDP, PCE inflation, and multinational enterprise activity in late November may clarify the economic trajectory. Uncertainty remains over whether rate hikes will slow inflation without triggering a recession.
The mixed market reaction on November 18, 2026, reflects a broader societal tension between inflation control and economic growth. Higher bond yields and falling gold prices may signal reduced safe-haven demand, potentially affecting retirement savings and long-term investment strategies, especially for risk-averse investors. The sharp decline in energy stocks, despite geopolitical risks, underscores how domestic supply data can override global concerns—potentially influencing energy policy debates and fuel pricing at the pump. Retail gains, driven by tariff refunds, may benefit consumers in the short term but could signal deeper trade policy shifts that affect global supply chains. The tech sector’s resilience, despite Nvidia’s drop, suggests that innovation remains a key market driver, though regulatory risks like export controls could deter future investment. A comparable earlier case is the 2022 market selloff, when hawkish Fed signals and oil volatility triggered widespread sell-offs. Looking ahead, the upcoming FOMC speeches and GDP data could determine whether markets shift toward optimism or renewed caution. The outcome may influence consumer confidence, hiring trends, and housing markets, with implications for household wealth and economic stability.