Earnouts and Escrow: The Real Story Behind HealthTech M&A Prices
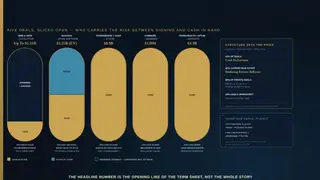
HealthTech M&A transactions frequently see a gap between announced enterprise value and actual seller proceeds, driven by earnouts, escrow, and working capital adjustments. The article presents five anonymized case studies illustrating common structural patterns in lower to mid-market deals. Strategic acquirers use these mechanisms to mitigate regulatory, reimbursement, and talent retention risks.
HealthTech acquisitions carry structural risks that generic M&A playbooks rarely address. Regulatory exposure may surface months after closing, payer and reimbursement shifts can alter the revenue base post-signing, and clinical or technical validation often remains incomplete at the deal date. Retention of specialized clinical and technical staff frequently constitutes the true asset being purchased, making talent risk a central pricing concern.
Earnouts appear in roughly 24% of non-life-sciences private-target deals, though this aggregate figure masks heavier concentration in categories like HealthTech where future performance depends on variables buyers cannot fully underwrite at signing—provider retention, payer contract renewals, and similar contingencies. The five composite case studies span AI-enabled revenue cycle management, value-based care, legacy SaaS, MedTech hardware, and early-stage AI diagnostics, each illustrating distinct structural mechanisms.
This reporting could reshape how founders and investors approach HealthTech exits, potentially reducing the shock of headline-versus-actual sale prices. If sellers enter negotiations with clearer expectations about escrow, earnouts, and working capital pegs, deal friction may decline and trust could improve. Patients and providers may indirectly benefit if smoother transactions preserve continuity of clinical services and technology platforms, though the opacity of these structures also raises questions about whether smaller sellers—and the communities they serve—bear disproportionate risk.