HealthTech Founders Face Tough Financing Choices in 2026
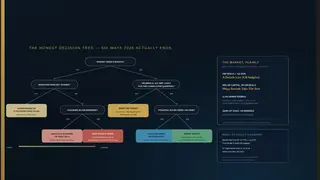
The article provides a decision framework for later-stage HealthTech founders considering down rounds, bridge financing, or strategic sales. It notes that capital is concentrated, with 19 companies absorbing 45% of digital health funding in H1 2026. Median deal size is $14 million, making it difficult for Series C companies to defend 2021 valuations.
The financing landscape for digital health companies has shifted dramatically since the 2021 peak. In the first half of 2026, $7.4 billion flowed into the sector across 244 deals, but the distribution was heavily skewed: 19 companies captured 45 percent of all capital through mega-deals exceeding $100 million. The median deal size of $14 million now resembles a typical Series A round, creating a mismatch for later-stage companies seeking growth capital.
Return expectations have also compressed sharply. Seed-stage multiples on invested capital dropped from roughly 14.5 times in 2021 to about 6.1 times by 2025, while Series A returns more than halved over the same period. This has made investors more disciplined about pricing risk, leaving founders with three realistic options: accept a down round, pursue bridge financing, or pursue a strategic sale.
The concentration of capital among a few category leaders could reshape the HealthTech ecosystem in ways that extend beyond individual companies. If mid-tier innovators struggle to secure funding, patients may see fewer novel digital health tools reach the market, while larger players consolidate their positions. Founders facing down rounds or strategic sales may need to weigh job impacts and product continuity against investor expectations. The shift toward disciplined pricing could ultimately produce a more sustainable sector, but the transition period may carry real consequences for innovation and access.