Retiring in Costa Rica on $2,500 a Month Requires More Savings Than It Seems
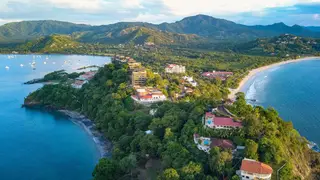
A $2,500 monthly budget in a secondary Costa Rican beach town covers about 1.13 million colones, but preserving purchasing power at age 59 could require roughly $1.69 million. Claiming Social Security at 62 would reduce the needed nest egg to about $708,000 because a $1,450 monthly benefit covers most of the $30,000 annual shortfall. Costa Rica's Rentista visa also requires a $60,000 two-year deposit that is spent on living costs, making a true no-drawdown retirement difficult before Social Security starts.
At prevailing exchange rates, $2,500 converts to about 1.13 million colones. A secondary Pacific beach town plan lists $1,000 for a two-bedroom, $250 for public health coverage, $450 for food, and $200 for utilities. Tamarindo or Flamingo would run higher, with two-bedroom units near the sand costing $1,500 to $3,000. Coastal air conditioning can add $60 to $150 each month.
A $579,000 Treasury ladder at 5.18% generates $30,000 yearly, yet inflation near 3.4% reduces its real value. Spending only the roughly 1.8% real return would need about $1.69 million. Taking Social Security at 62 lowers the required amount to roughly $708,000. Costa Rica's Rentista visa also mandates a $60,000 two-year deposit that is consumed by living expenses.
This story may influence near-retirees weighing early retirement abroad, especially those who assume a modest monthly budget equals a simple nest-egg target. It could prompt more careful planning around inflation, visa deposits, health costs, and Social Security timing. Costa Rican beach communities might see continued demand from expatriates, while local rental and health-service markets could feel pressure. The broader effect may be greater awareness that retirement affordability depends on preserving purchasing power, not just covering monthly expenses.