ON Semiconductor's AI Data Center Growth May Be Underpriced
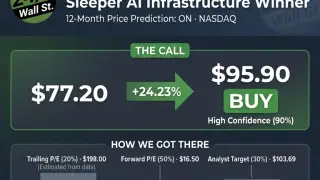
ON Semiconductor trades 43% below its 52-week high, but its AI data center business is expected to more than double in 2026, supporting a $95.90 price target. The stock trades at 17x forward earnings, below Texas Instruments at 28x and Analog Devices at 23x. Silicon carbide content per AI rack could rise from $15,000 to $115,000 as data centers adopt 800-volt DC power, driving nearly 60% SiC revenue growth in 2026.
ON Semiconductor's stock sits roughly 43% below its 52-week peak, yet its AI data-center business is expected to more than double in 2026. A $95.90 target implies about 24% upside from $77.20.
Its 17x forward earnings multiple trails Texas Instruments at 28x and Analog Devices at 23x. Silicon carbide content per AI rack may climb from $15,000 to $115,000 as 800-volt DC power spreads, potentially lifting SiC data-center revenue nearly 60% in 2026.
If ON Semiconductor's AI power and silicon carbide forecasts materialize, data-center operators and chip investors could be affected. More efficient 800-volt DC power may reduce energy losses in AI facilities, potentially lowering operating costs and supporting grid demand management. Auto-focused suppliers and workers may see shifting demand as capacity moves toward data-center components. However, execution risks, customer concentration, and cyclical automotive exposure mean these outcomes may not reach society evenly or quickly.