Hinge Health blends virtual-care automation with targeted device acquisitions to scale digital healthcare
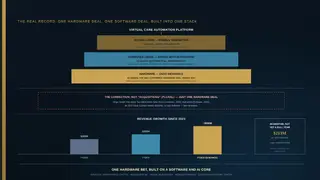
Hinge Health has grown from a digital musculoskeletal clinic into a larger virtual-care provider serving multiple conditions. Its strategy combines automation that sharply reduces clinician labor hours with purchases of therapeutic hardware, such as the Enso wearable, and the acquisition of Cylinder Health. After its May 2025 IPO, the company's stock gained more than 200%, giving it a market value near $8 billion and supporting a fiscal 2026 revenue target of about $858 million.
Hinge Health began as a digital clinic focused on musculoskeletal care, then broadened into virtual treatment for several conditions. Its model combines software automation with selected purchases of therapeutic devices, including the Enso wearable, and the acquisition of Cylinder Health for $105 million in cash.
After listing in May 2025 at $32 per share, the company’s shares rose over 200%, lifting its value to roughly $8 billion. Management aims for about $858 million in fiscal 2026 revenue, 46% annual growth, and long-term operating margins of at least 35%.
Hinge Health’s automation-heavy virtual care could broaden access to musculoskeletal and other specialty treatment, especially for people facing travel, cost, or scheduling barriers. If device-supported programs improve adherence, employers and insurers may see different utilization and spending patterns. Yet the model may also raise questions about clinician oversight, data collection from wearables, and whether digital-first care reaches populations with limited technology access. Its growth could influence how other health systems balance automation, hardware, and human care.